Car Loans in Wetaskiwin, Alberta: A Straightforward Guide for Local Buyers
10 October 2026Wetaskiwin sits right where a lot of central Alberta life happens: a short drive to Leduc and the Nisku industrial area, about an hour to Edmonton, and surrounded by farms, acreages and the Pigeon Lake cabin crowd. Whether you commute up Highway 2A every morning or haul feed on gravel roads, you need a vehicle you can count on and a loan you can actually afford. This guide covers how car financing works for Wetaskiwin buyers and how to put yourself in a good position before you sign anything.
Ready to check your options now? Start your application here.
How a car loan works in Alberta
A car loan is an instalment loan secured by the vehicle. You borrow the purchase price (minus any down payment or trade-in), then repay it with interest over a set term, usually between 36 and 84 months. Until it's paid off, the lender holds a lien on the vehicle.
Alberta has one tax advantage worth knowing: there's no provincial sales tax, so you pay only the 5 percent GST on a dealer purchase. On a $30,000 truck, that's thousands less than buyers pay in BC or Saskatchewan, which means less to finance.
What lenders look at
- Credit history. Your score and how you've handled payments in the past. Strong credit gets the best rates, but fair or rebuilding credit can still be approved.
- Income. Pay stubs, a job letter, or tax returns if you're self-employed or farming. Lenders want to see that the payment fits comfortably.
- Employment stability. Oilfield, trades and agriculture work can be seasonal or contract-based. That's fine. Showing a steady history in your field helps.
- Debt-to-income ratio. Your existing payments compared to what you earn.
- Down payment and trade-in. Both reduce what you borrow and can improve your rate.
Picking the right term
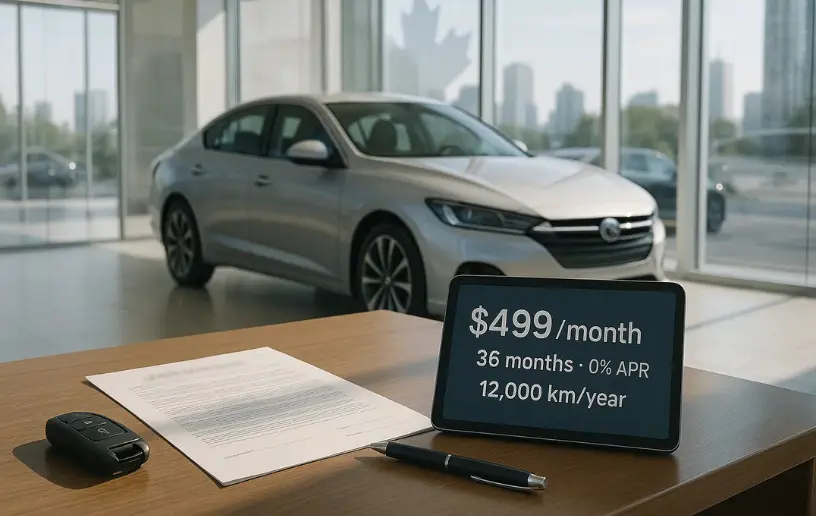
A longer term lowers your monthly payment but raises the total interest you pay. For example, a $28,000 loan at 8 percent costs roughly $568 a month over 60 months and about $437 a month over 84 months. The 84-month option saves you around $130 a month, but you'll pay roughly $2,600 more in interest and stay upside down on the loan longer.
A good rule: choose the shortest term whose payment still fits your budget with room to spare.
Budgeting for the real cost
Your loan payment is only part of what it costs to drive. In Wetaskiwin, factor in:
- Insurance. Alberta uses private insurers, so shop around. Rates vary by age, driving record and vehicle.
- Fuel. Long commutes to Leduc, Nisku or Edmonton add up, so fuel economy matters.
- Winter costs. Block heater, winter tires and the occasional tow on a cold morning.
- Maintenance. Gravel roads are hard on suspensions, windshields and paint.
Try to keep your total vehicle costs to around 15 to 20 percent of your take-home pay.
Choosing a vehicle that fits life around Wetaskiwin
Half-ton pickups and AWD SUVs are popular here for good reason. They handle snow, gravel and towing a boat out to Pigeon Lake. If you mostly commute on pavement, a fuel-efficient crossover or sedan can save you a lot each month. Whatever you choose:
- Get a vehicle history report and a pre-purchase inspection on anything used.
- Check for rust and underbody damage from salted winter roads.
- Don't let a big truck push your payment past what's comfortable.
If a pickup is on your list, our pickup truck financing guide walks through terms and down payments.
Financing with less-than-perfect credit
If your credit has some bruises, you're not out of options. Lenders who specialize in non-prime auto loans look at your current income and stability, not just old mistakes. Expect a higher rate at first, and plan to refinance after 12 to 18 months of on-time payments. Steps that help:
- Check your Equifax and TransUnion reports for errors.
- Save even a modest down payment.
- Choose a practical vehicle priced within your budget.
- Bring complete documents to avoid delays.
Should you buy locally or in Edmonton?
Wetaskiwin has local dealerships, and the bigger lots in Leduc and south Edmonton are close by. More inventory can mean better selection and pricing, but local dealers often make service easier. Financing works the same either way. Many buyers also compare against nearby markets; our Leduc car loan guide and Camrose car loan guide cover those areas.
Common questions
Can I get a car loan if I'm self-employed or farming?
Yes. Lenders usually ask for two years of tax returns or Notices of Assessment and recent bank statements to confirm income.
How much down payment do I need?
There's no fixed minimum. Ten to twenty percent is ideal, but many buyers are approved with less when income is solid.
Can I trade in a vehicle I still owe money on?
Usually, yes. The remaining balance gets paid off and any equity, or shortfall, is rolled into the new deal. Try to avoid rolling over a large shortfall.
Get pre-approved before you shop
Knowing your budget before you walk onto a lot puts you in control of the conversation. Auto Lending Canada helps buyers across BC, Alberta and Saskatchewan, including Wetaskiwin and the surrounding county, find financing that fits their situation. Start your application here.