
Is Gap Insurance Worth It in Canada? What It Covers and When to Skip It
14 September 2026Gap insurance gets pitched at almost every dealership finance desk in the country, usually right after you've agreed on a vehicle price and your guard is already down. Some buyers genuinely need it. A lot of buyers get talked into it without anyone explaining what it actually covers, or checking whether their existing policy already covers the same thing for less. Here's the honest version.
What Gap Insurance Actually Does
Standard auto insurance pays out the actual cash value of your vehicle if it's stolen or written off, meaning what it's worth on the used market at the moment of the loss, not what you paid for it and definitely not what you still owe on the loan. Gap insurance, short for Guaranteed Asset Protection, covers the difference between that payout and your remaining loan balance.
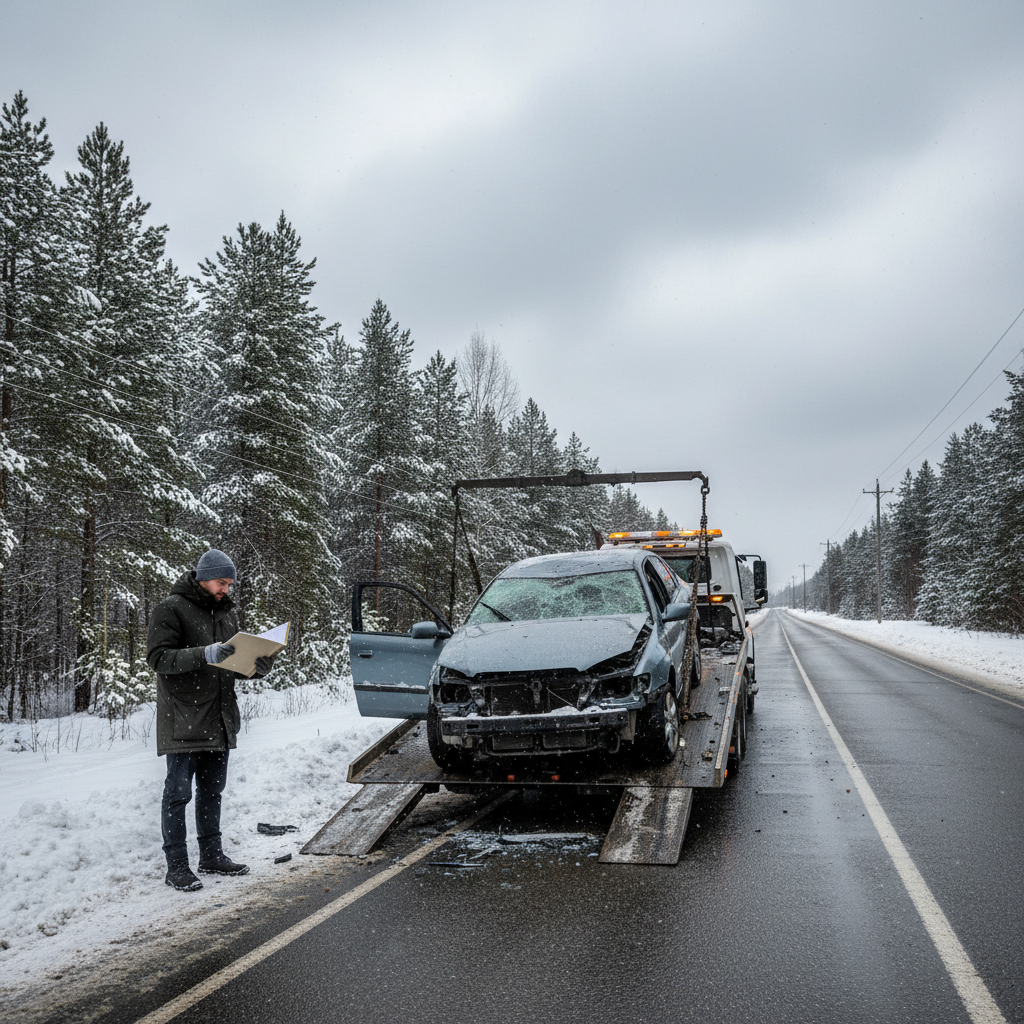
Say your car gets totaled eighteen months into a five-year loan. Your insurer's actual cash value payout comes to $19,000. You still owe $24,000 on the loan. Without gap coverage, you owe your lender that $5,000 difference out of pocket, on a car you no longer have. With gap coverage, the policy covers that gap instead of you.
When It Actually Makes Sense
Gap insurance earns its cost in a fairly specific set of situations, and it's worth being honest about which one you're actually in before adding it to your loan.
- You put little or nothing down. A small down payment means you start the loan already close to the vehicle's value, so it takes almost nothing in early depreciation to put you underwater.
- You financed over a long term. A 72 or 84-month loan keeps your balance high for years while the car's value keeps dropping, which is exactly the gap this coverage is built for. Our piece on the hidden cost of 84-month car loans covers why that structure creates this exposure in the first place.
- You bought a new vehicle. New cars lose the steepest chunk of their value in the first year or two, which is precisely when the gap between loan balance and market value is widest.
- You rolled negative equity from a previous trade-in into this loan. If you're carrying old debt on top of a new purchase, your loan-to-value ratio starts underwater from day one, which is the exact scenario gap insurance exists for.
When You Can Probably Skip It
If you put down 20% or more, financed over a standard 48 to 60-month term, or you're buying a used vehicle that's already done most of its depreciating, the math usually doesn't favour gap insurance. In these cases your loan balance and the car's actual value stay reasonably close together for most of the term, so there's rarely a meaningful gap for the coverage to fill.
It's also worth checking your existing auto insurance policy before adding anything. Some insurers offer a similar product, sometimes called loan/lease payout coverage, built into a policy add-on that costs less than a dealership's gap insurance premium. A five-minute call to your existing insurer before you sign anything at the dealership can save real money either way.
Dealership Price vs. Insurer Price
This is the part that catches people off guard. Gap insurance sold at a dealership finance desk, often bundled quietly into your monthly payment, frequently costs several times what the same or similar coverage costs as a standalone policy add-on through your existing auto insurer. Dealership gap coverage might run several hundred to over a thousand dollars as a lump sum rolled into your loan (with interest accruing on it for the life of the loan), while insurer-based coverage is often a modest amount added to your existing premium.
Before agreeing to anything at the dealership, it's worth asking your current insurer for a quote on the same coverage. If the numbers are close, dealership convenience might tip the decision. If they're not close, and they often aren't, that's real money staying in your pocket for the cost of one phone call.
What Gap Insurance Doesn't Cover
It's worth being clear on the limits too. Gap insurance doesn't cover your insurance deductible, missed or late payments that added to your balance, extended warranty or other add-on products rolled into the loan, or negative equity from a previous vehicle that was already rolled into this one before the policy started. It also generally only applies to a total loss or theft, not routine wear, mechanical issues, or a voluntary trade-in.
How to Decide
Pull up your current loan balance and compare it honestly against what your vehicle would actually sell for today. If that gap is a few thousand dollars or more, and especially if you're early in a long loan term with a small down payment, gap insurance is doing real work for the cost. If the gap is small or nonexistent, you're likely paying for coverage against a scenario that can't really happen to you right now.
Whatever you decide, get a quote from your existing insurer before accepting a dealership's number as the only option on the table.
Auto Lending Canada helps drivers across British Columbia, Alberta, and Saskatchewan structure loans that avoid unnecessary long-term exposure in the first place, with reasonable terms and down payments that keep you above water. Start your application here to see what a properly structured loan looks like for your situation.












