
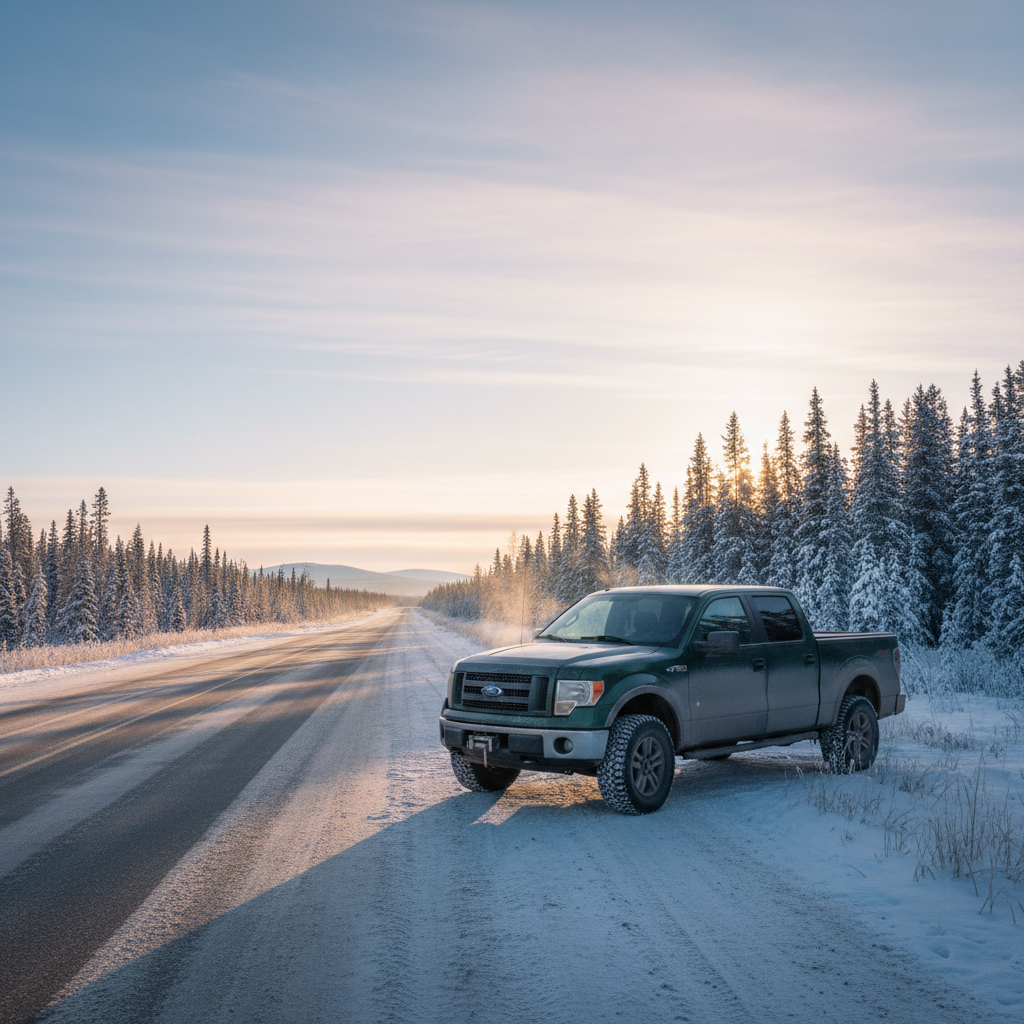
Car Loans in Fort McMurray, Alberta: Rates, Requirements, and How to Apply
26 September 2026Fort McMurray is a working city. Shift schedules, contractor gigs, and resource-sector income are part of daily life — and so is needing a truck or reliable car that can handle winter roads and long drives between site, town, and family commitments. Getting a car loan in Fort McMurray follows Alberta underwriting rules, with a few local patterns around income proof and vehicle type that are worth knowing before you walk into a dealer.
Here is how rates and requirements usually work for Fort McMurray buyers, what lenders ask for, and a practical way to apply without wasting weekends on dead ends.
How car loans work in Fort McMurray
Whether you buy at a local lot or arrange financing first, lenders still look at credit score, income, debt load, and the vehicle. Specialty auto lenders and broker networks that already fund Alberta files can be useful when a big bank’s cut-off is too rigid for shift or contract income.
If you have already compared options in Edmonton or elsewhere in the province, the same document checklist applies up north. Our Edmonton car loan guide covers the Alberta process in more detail; this page focuses on what Fort McMurray shoppers specifically run into.
Start your application here when you know the vehicle category you want — truck, SUV, or car — so lenders can price the right structure.
Income patterns lenders see from Wood Buffalo
Resource and trades income is often strong on paper but lumpy in the bank account. Camp pay, overtime, and short-term contracts can look excellent in a good month and thin in a quiet one. Lenders care less about the industry name and more about:
- Recent pay stubs or contractor invoices that show current earnings
- Bank deposits that match what you claim
- How long you have been with your current employer or on your current contract
- Whether overtime or camp pay is consistent enough to count toward the payment
If employment verification has slowed you down before, read how employment verification works on Canadian car loans so you know what to have ready. Self-employed contractors should also expect questions about GST filings and average monthly deposits, not just a single high invoice.
Rates, credit, and vehicle choice up north
Alberta rates still track credit score and loan-to-value. A stronger score and a reasonable down payment usually mean a better buy rate. Choosing a truck or higher-kilometre used vehicle can change how much a lender will advance — useful to know in a region where pickups are common work tools rather than weekend toys.
For a sense of how pricing moves with score bands, see car loan rates by credit score in Canada. If credit is the sticking point, also review bad credit car loans in Canada before you commit to a payment you cannot sustain through a slow season.
Dealers, banks, and shopping multiple lenders
Fort McMurray has local dealerships and access to lenders who fund Alberta province-wide. A single dealer desk may only submit to a handful of finance sources. Getting an independent quote first gives you a benchmark when someone offers a “today only” rate on the lot.
Hard inquiries add up if you apply at every bank branch yourself. A broker-style submission that reaches several lenders under one process can reduce that noise while still letting you compare structures — term, rate, and required down payment included.
Practical tips for Fort McMurray buyers
- Get pre-qualified before you fall in love with a specific unit on a lot.
- Budget for insurance, winter tires, and fuel — not just the loan payment. Northern driving costs more than the advertisement suggests.
- Keep term length realistic. A longer term lowers the monthly number but increases total interest paid.
- If you are on a rotating shift, make sure payment dates align with when money hits your account.
- Compare dealer financing against an independent quote so you know whether the special rate is actually special.
- Be honest about existing debts. Surprises on the credit bureau slow everything down.
Documents to have ready
Most Fort McMurray approvals move faster when you arrive with:
- Government ID and proof of Alberta address
- Two or more recent pay stubs, or invoices plus bank statements for contract work
- A rough vehicle budget and preferred body style
- Details on any co-applicant if you plan to apply jointly
Nobody can promise approval. What you can control is presenting a complete, accurate file.
Trucks vs cars in Fort McMurray financing
Many Wood Buffalo buyers need a half-ton for work, winter, or both. Lenders will fund trucks, but they price mileage, trim, and remaining useful life carefully. A high-kilometre work truck can still be financeable with enough down payment; a brand-new loaded unit on thin credit is a harder ask.
If your commute is mostly in town and you do not need payload, a simpler SUV or car can open more lender options and lower insurance. Match the vehicle to the job, then match the loan to the vehicle — not the other way around.
Avoiding expensive surprises on the lot
Northern buyers sometimes accept the first approval because travel time and shift schedules make shopping painful. That convenience has a cost when the rate is padded or the term is stretched without discussion. Ask for the annual percentage rate, the term in months, the total amount financed, and whether any products were added to the loan.
If the payment only works with an 84- or 96-month term on a used unit, recalculate with a cheaper vehicle or a larger down payment before you sign.
Apply with a complete file
Auto Lending Canada works with drivers across Alberta, British Columbia, and Saskatchewan — including northern and resource communities — to match files with lenders who already fund those profiles. If you need a truck or daily driver for life in Fort McMurray, start with clear numbers and let lenders respond to your real situation.












