
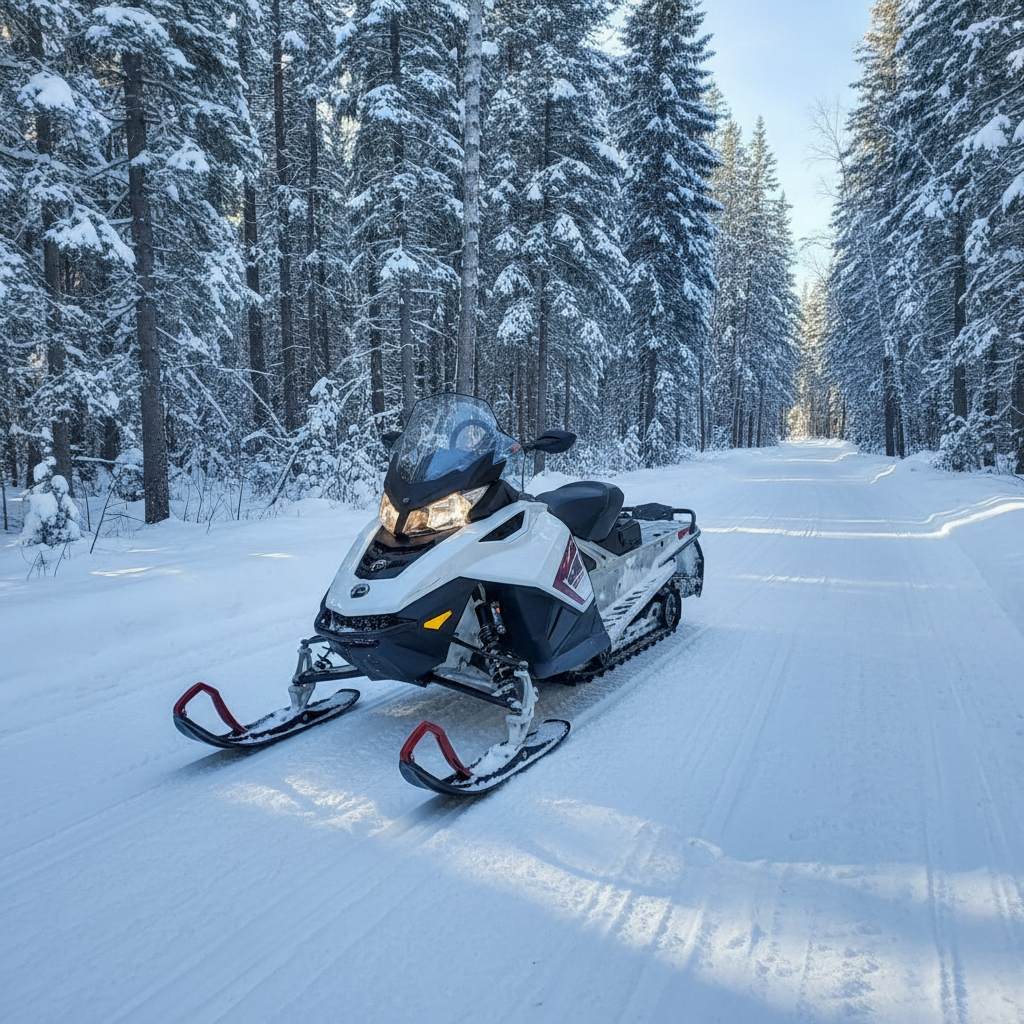
Snowmobile Financing in Canada: Loans, Terms, and How to Qualify
28 September 2026Snowmobiles are winter workhorses for some Canadians and weekend trail machines for others. Either way, paying cash is not always realistic — and financing a sled is not identical to financing a daily driver. Lenders treat powersports collateral differently, terms are often shorter, and approval depends as much on the machine’s age, hours, and seasonal use as on your credit score.
If you are shopping a snowmobile in British Columbia, Alberta, or Saskatchewan, this guide covers how snowmobile loans typically work, what underwriters look for, and how to apply without wasting hard inquiries.
Start your application here when you know the type of machine you want — you can refine the model after a lender reviews your file.
How snowmobile financing usually works in Canada
Most snowmobile loans are secured against the unit. You borrow a set amount, make fixed payments over a term, and the lender holds a security interest until the balance is paid. Compared with car loans, you will often see:
- Shorter maximum terms
- Stricter age and hour caps on used machines
- Fewer prime bank programs and more specialty or powersports-focused lenders
- Higher rates when the sled is purely recreational rather than clearly tied to property or work access
For the wider powersports picture — including ATVs and side-by-sides — see how to finance powersports vehicles in Canada.
What lenders look for on a snowmobile application
Expect the usual underwriting pillars, with powersports twists:
- Credit score and history: Late payments and thin files still matter. Specialty lenders may work with fair credit when the rest of the file is strong.
- Income and debt: The sled payment has to fit beside your existing car loan, rent or mortgage, and other obligations — even in months you are not riding.
- Down payment: More cash down helps on older or higher-hour machines.
- Machine details: Year, make, model, hours, and whether it is new or used.
- Intended use: Remote property access or work use can be viewed differently from pure recreation, depending on the lender.
ATV and motorcycle programs follow a similar specialty path. If you are comparing machines, our guides to ATV financing in Canada and motorcycle financing show how those products typically differ from car loans.
Seasonal use in BC, Alberta, and Saskatchewan winters
Snowmobile season is short relative to a twelve-month loan. Lenders still expect year-round payments. Budget for storage, trail permits, gear, and maintenance in the off-season so the payment does not collide with summer vacation spending or a second powersports purchase.
In the Rockies, northern BC, Alberta foothills, and Saskatchewan trail networks, sleds earn their keep for recreation and sometimes for accessing remote property. Be clear about use on the application. Misrepresenting work use when the machine is recreational can cause funding problems later.
New vs used snowmobile loans
New sleds may come with manufacturer finance promotions if your credit qualifies. Used machines cost less up front but often face tighter caps — many lenders will not fund very old or high-hour units, or they will require a larger down payment. Get the VIN/serial, hour meter reading, and a clear bill of sale ready before you apply.
Private-sale purchases can be financed in some programs, but not all. Dealer purchases are usually simpler because the paperwork and lien registration are familiar to the lender.
Rates, terms, and total cost
Advertised powersports rates are starting points, not promises. Your rate will reflect credit strength, down payment, and the machine. Shorter terms mean higher monthly payments but less interest over the life of the loan. Stretching the term to chase a low monthly number can leave you owing more than the sled is worth if you sell early.
Insurance and registration rules vary by province and by whether the snowmobile is used on private land, trails, or roads. Budget for those costs before you lock a payment.
Practical tips before you apply
- Know the exact machine details — year, hours, and asking price — before you submit.
- Check your Equifax and TransUnion scores so the conversation stays realistic.
- Set a payment that still works after trail fees, gear, storage, and your car payment.
- Avoid stacking multiple hard inquiries across every dealer in one weekend.
- Be honest about intended use and about whether this is a second recreational unit on top of an existing auto loan.
When you are ready to submit, follow the same accuracy standards in how to apply for a car loan in Canada — incomplete powersports apps get delayed just as fast as car apps.
Who snowmobile financing suits
Snowmobile financing is a practical fit when you need the machine for winter access or recreation and can prove income that covers the payment year-round. It is a weaker fit if the only way the numbers work is a very long term on an older unit a lender will not fund. Approval is never guaranteed — present a complete file and pick a machine within the program’s age and advance limits.
Trail networks and Western Canada use cases
In British Columbia, Alberta, and Saskatchewan, snowmobiles show up on recreational trail networks, remote acreages, and winter access routes where trucks cannot go. If the machine is clearly tied to property access or seasonal work, say so clearly on the application and be ready to describe how you use it. Lenders still underwrite the payment against your income — they do not treat a sled like a free pass — but accurate use details help them place the file in the right program.
Recreational-only purchases are still financed every week. Just expect the same scrutiny on credit, down payment, and machine age that you would see on other powersports deals. Pairing a new sled payment with an existing truck loan and a second recreational unit is where many files get tight — run the full household payment stack before you submit.
Ready to finance a snowmobile?
Auto Lending Canada helps drivers and powersports buyers across British Columbia, Alberta, and Saskatchewan compare loan options. When you are ready, submit a clear application and let lenders respond to your real numbers.












