
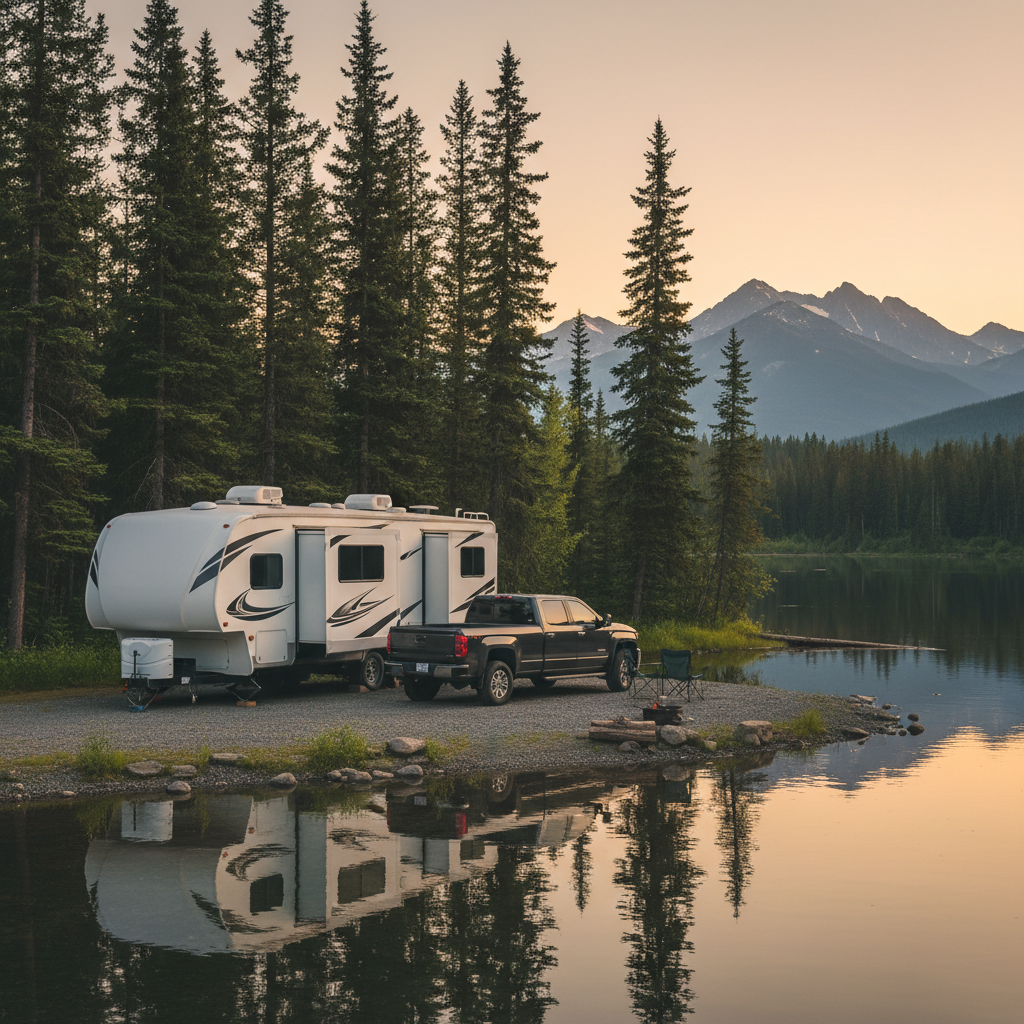
Fifth Wheel Financing in Canada: Loan Terms, Down Payments, and Approval Tips
06 October 2026A fifth wheel gives you more living space than almost any towable RV. High ceilings, residential-style kitchens, and separate bedrooms make it a favourite for families who camp all summer and retirees who spend months on the road. It's also one of the bigger purchases you can make outside a house, which is why most buyers finance it.
This guide covers how fifth wheel loans work in Canada, what lenders look for, and how to keep the total cost in check. If you're ready to see what you qualify for, you can start a quick application here.
How fifth wheel loans work
A fifth wheel loan is a secured loan, much like a car loan. The trailer itself is the collateral, so the lender registers a lien on it until it's paid off. You make fixed monthly payments over a set term, and once the loan is paid, the lien is released.
The main differences from a car loan are the size and length. Fifth wheels commonly cost anywhere from about $40,000 for a used model to well over $100,000 new. Because the amounts are bigger, lenders often offer longer terms than they would on a car, sometimes 10 to 15 years or more on newer, higher-priced units. That keeps the payment down, but it also means you'll pay a lot more interest over the life of the loan.
What lenders check
Credit
RV lenders tend to be a bit more conservative than auto lenders, since a fifth wheel is a recreational purchase rather than something you need to get to work. A score in the high 600s or better usually gets the best terms. Lower scores can still get approved, but expect a higher rate, a bigger down payment, or a shorter term.
Income and debt
Lenders will look at your income and your total monthly debt, including your mortgage or rent, any car or truck payment, and the new trailer payment. If you also need to finance a tow vehicle, both loans count, so plan them together.
The unit itself
Age, condition, and value all matter. Many lenders limit how old a used RV can be or shorten the term on older units. A professional inspection before you buy protects both you and the lender, especially for roof seals, slide-outs, and water damage, which are common and expensive problems on used fifth wheels.
How much should you put down?
Down payments of 10% to 20% are typical for RV loans. Putting more down does three useful things:
- It lowers your monthly payment and total interest.
- It can get you a better rate, particularly if your credit isn't perfect.
- It protects you from depreciation. Fifth wheels lose value quickly in the first few years, and a small down payment on a long loan can leave you owing more than the trailer is worth.
For more on how down payments change your loan, see our guide to down payments in Canada. The same logic applies to RVs.
Don't forget the truck
A fifth wheel needs a pickup with a hitch mounted in the bed, and many larger units need a three-quarter-ton or one-ton truck to tow safely. If your current truck isn't rated for the weight you're considering, you could be looking at two purchases instead of one.
Before you shop for a trailer, check your truck's towing and payload ratings in the owner's manual or on the door jamb sticker. Payload is often the limit people run into first, because the pin weight of a fifth wheel sits directly in the truck bed. If you need a new truck too, our guide to pickup truck financing in Canada walks through what lenders look for.
Fifth wheel vs. travel trailer vs. toy hauler
If you're still deciding on the type of RV, it helps to compare how they finance:
- Travel trailers are usually lighter and cheaper, tow with a regular hitch, and often work with a half-ton truck or large SUV. Smaller loans mean easier approvals. Our RV and travel trailer financing guide covers these.
- Fifth wheels offer more space and stable towing but need a pickup and usually cost more.
- Toy haulers add a garage for ATVs or dirt bikes, and many come in fifth wheel form. See our guide to toy hauler financing if you're bringing toys along.
The full cost of owning a fifth wheel
The loan payment is only part of it. Before you sign, budget for:
- Insurance. Rates depend on the unit's value and how you use it. Full-time living usually costs more to insure than seasonal camping.
- Storage. Many towns and strata properties don't allow RV parking on the street or in driveways, so you may need to pay for a storage lot.
- Maintenance. Roof inspections, bearing service, tires, and winterizing every fall add up.
- Fuel. Towing a heavy fifth wheel can cut your truck's fuel economy dramatically.
- Campground fees. Full-hookup sites at popular parks in BC and Alberta can be pricey in peak season.
Tips for getting approved
- Know your budget first. Work out what payment you can carry alongside your truck and housing costs, then shop within it.
- Get pre-approved before you visit an RV show or dealer, so a sales event doesn't set your budget for you.
- Consider a lightly used unit. A two- to five-year-old fifth wheel has already taken its biggest depreciation hit.
- Keep the term reasonable. A long term makes the payment easy, but compare the total interest on a 10-year and a 15-year loan before deciding.
- Read the loan terms. Check for prepayment penalties so you can pay it off early if you want to.
Ready to hit the road?
A fifth wheel can turn summer weekends into proper trips and make long stays on the road comfortable. Financing it wisely means looking at the trailer, the truck, and the running costs together, so the payment fits your life instead of stretching it.
Auto Lending Canada helps buyers across British Columbia, Alberta and Saskatchewan finance RVs, trailers, trucks and cars, with options for a range of credit profiles. It's free to apply and there's no obligation. Start your application here.












